Global Crop Prices Post Largest Quarterly Jump Since Ukraine Invasion
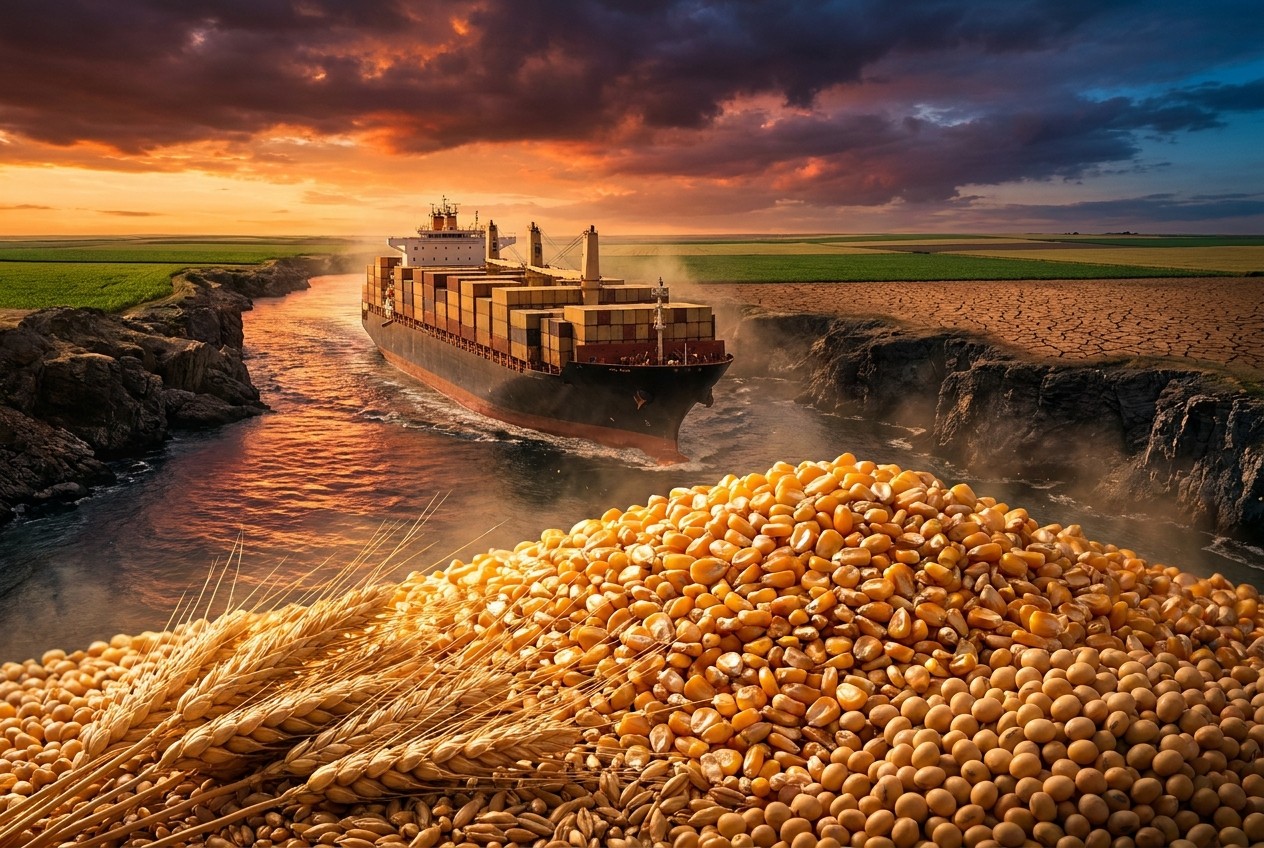
European crop producers and farm managers are facing a rapidly shifting economic landscape as international commodity markets register their most volatile quarter in years. According to the Bloomberg Agriculture Spot Index, global crop prices surged 13% over the third quarter, marking the sharpest quarterly advance since Russia's invasion of Ukraine in early 2022. This upward pressure is fundamentally altering input-output cost calculations for grain, oilseed, and specialty crop producers across the European Union and neighboring regions.
The primary driver behind this sharp price correction lies in a convergence of severe weather events and tightening global inventories. Major agricultural exporting regions in Eastern Europe, parts of South America, and North America have battled persistent droughts, excessive heatwaves, and untimely precipitation during critical growing and harvesting stages. These localized climatic shocks have collectively degraded expected yields for key staples like wheat, corn, and soybeans, pulling global stockpiles down to uncomfortable thresholds for grain traders and processors.
For European agronomists and farm directors, this price surge presents a complex operational dilemma. On one hand, higher market values for grains and oilseeds promise improved revenue potentials for operations that managed to protect their yields against adverse weather. On the other hand, the volatility makes forward contracting and risk management exceptionally challenging. Farmers must carefully weigh the costs of intensive input management—such as targeted fertilization and advanced crop protection—against unpredictable market trajectories and fluctuating local basis prices.
At the farm gate level, the impact of these surging indices is highly localized and depends heavily on regional logistics and storage capacities. Producers in Poland, Romania, and Ukraine are closely monitoring export corridor capacities and regional demand from feed mills and processing plants. While grain producers may see immediate financial relief after seasons marked by depressed margins, livestock and dairy farmers face mounting margin pressures as feed grain costs escalate rapidly across Western and Central Europe.
What this means for the market: Farm enterprises should review their commercialization strategies and consider locking in partial sales to hedge against sudden market corrections while protecting profitability margins. Agronomists and farm managers must simultaneously tighten inventory controls and optimize fertilizer efficiency to maximize output value during this period of high agricultural volatility.
— agronom.work editorial team