Global Edible Oil Market Faces Volatility as El Niño and Biodiesel Mandates Loom
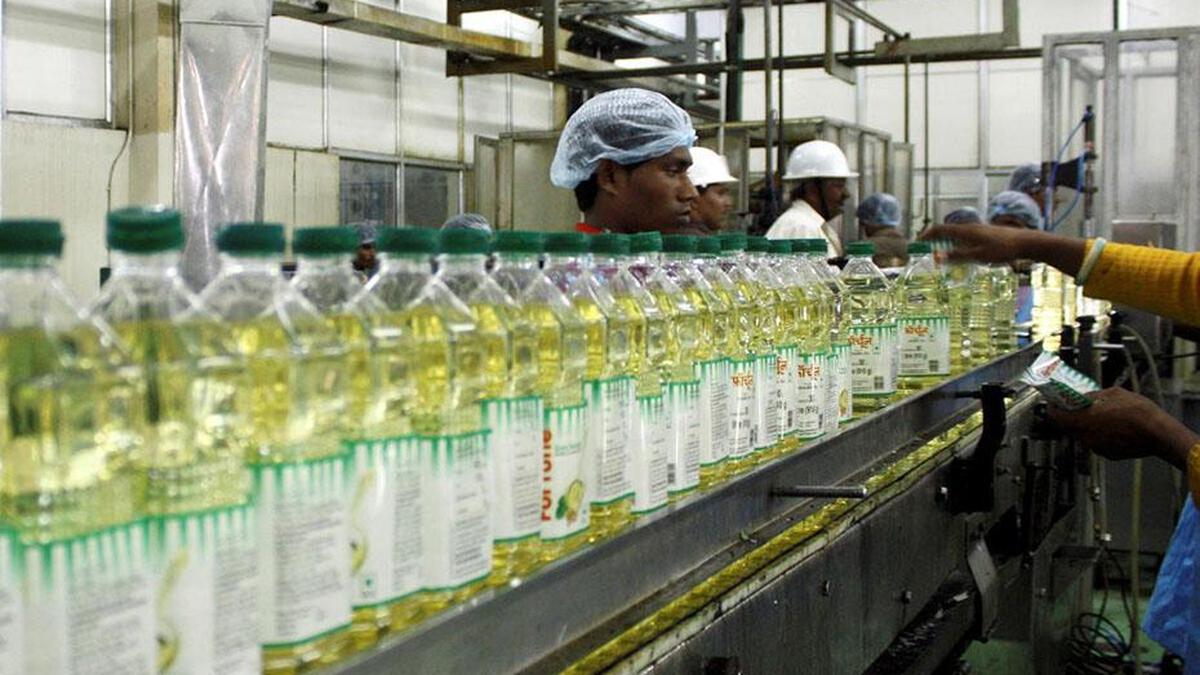
European grain traders, oilseed crushers, and agricultural producers are keeping a close eye on international vegetable oil markets following recent warnings from the Solvent Extractors Association of India. Industry leaders have pointed to a convergence of compounding risk factors—ranging from erratic weather phenomena to shifting government mandates—that threaten to upend global supply chains and price stability for soft oils in the upcoming marketing year.
A primary driver of this anticipated market turbulence is the lingering threat of El Niño, which historically disrupts precipitation patterns across major agricultural zones in Southeast Asia and the Americas. Such weather anomalies directly impact palm oil yields in Indonesia and Malaysia, as well as soybean production in South America, tightening global export availability and forcing food manufacturers and feed compounders to seek alternative lipid sources.
Simultaneously, the persistent geopolitical instability in the Black Sea region continues to cast a shadow over sunflower oil trade flows. Ukraine and Russia remain crucial suppliers of sunoil to European and global destinations, and any logistics bottlenecks, infrastructure damage, or export policy shifts immediately ripple through the entire edible oil complex, affecting rapeseed and soybean values across EU domestic markets.
Adding further pressure to global inventories is Indonesia's ambitious B50 biodiesel program. By significantly increasing domestic blending mandates from B35 to B50, Jakarta will inevitably divert substantial volumes of crude palm oil away from the export market and into domestic energy channels. For European importers who rely heavily on palm oil for both food processing and industrial applications, this policy shift means tighter supplies and heightened competition for substitute oils.
For European farmers and agronomists, these global macro trends directly translate into shifting crop profitability and input dynamics. Higher global vegetable oil prices can stimulate increased domestic demand and attractive pricing for EU oilseeds like rapeseed and high-oleic sunflower, while simultaneously influencing the cost of imported feed ingredients for livestock producers across the continent.
What this means for the market: European producers of rapeseed and sunflower should closely monitor international crush margins and palm oil export restrictions, as tightening global supplies could offer favorable domestic pricing opportunities during the upcoming marketing season.
— agronom.work editorial team