India's Dairy Export Ambitions: What It Means for Global Dairy Markets
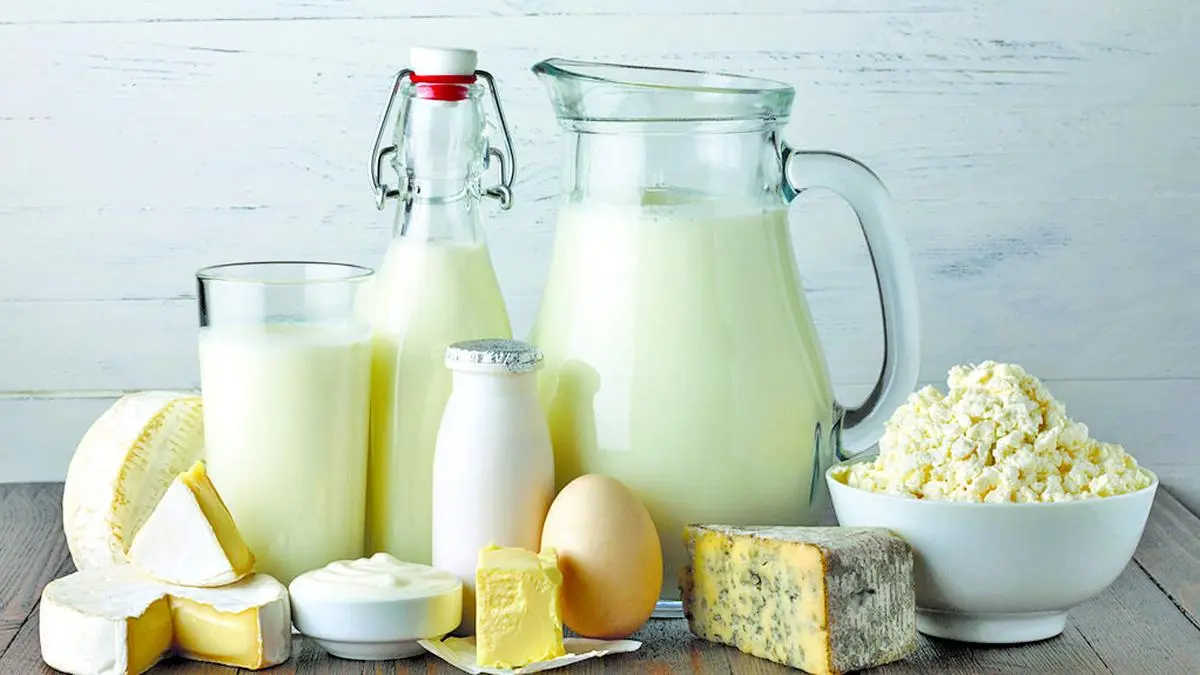
India has long been a dairy powerhouse by volume, producing an impressive 247.87 million tonnes of milk in the 2024-25 fiscal year. This massive output accounts for nearly a quarter of the entire global production, driven by millions of smallholder dairy farmers across the country. Yet, despite being the world's leading milk producer, India has traditionally remained a localized market, exporting less than one percent of its total dairy yield.
A strategic shift is now underway, centered around Anhydrous Milk Fat (AMF), butter, and ghee, which hit a domestic output of 5.1 million tonnes. Agricultural strategists in New Delhi are mapping out a calculated export roadmap. The primary defensive objective is securing dominance in neighboring South Asia, particularly Bangladesh, while expanding footprint into the lucrative Gulf markets. Simultaneously, longer-term positioning is being considered for Southeast Asia, Africa, and potentially China.
For European dairy farmers, cooperatives, and major processors in dairy-heavy nations like the Netherlands, Germany, and Poland, India's export push introduces a new competitive dynamic on the global stage. While Europe remains a dominant exporter of high-value cheese, specialized powders, and infant formula, an aggressive push by India into bulk dairy fats could alter price ceilings in developing import markets across Asia and Africa.
AMF and butter oil serve as critical raw materials for industrial food manufacturing, repackaging, and recombination into liquid milk in deficit regions. If Indian cooperatives can scale their export supply chains and meet stringent international sanitary and phytosanitary standards consistently, they could capture significant market share in price-sensitive importing countries, putting pressure on global commodity quotes managed by European and Oceanian traders.
At the same time, structural hurdles remain formidable. India’s domestic consumption continues to grow rapidly alongside rising incomes, meaning export surpluses can fluctuate based on local weather patterns, monsoon success, and domestic feed costs. Furthermore, animal health standards and traceability requirements in high-end markets will require massive investments in farm-level infrastructure before Indian dairy can compete directly with European quality benchmarks.
Context for farmers: While Indian dairy expansion is unlikely to flood European domestic shelves directly, it signals intensifying competition in traditional export destinations across Asia and the Middle East, which could influence global butter and milk fat price trends heading into the next production season.
— agronom.work editorial team